
Written by the NewsMagToday Content Team | Reviewed by Rohit Negi, Insurance Expert | Last updated: October 2026
Quick Answer
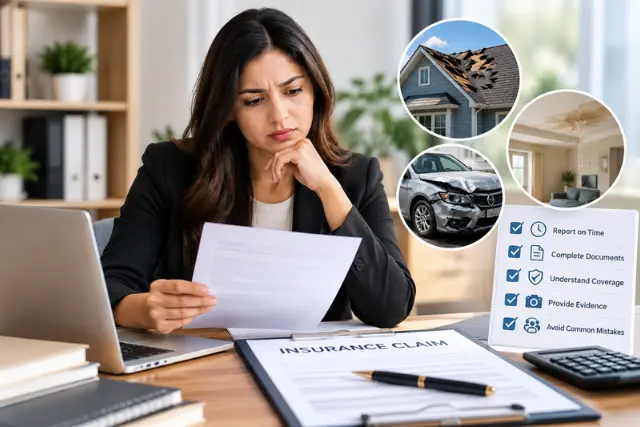
Common mistakes in insurance claims include reporting a loss too late, submitting incomplete documentation, misunderstanding what your policy actually covers, exaggerating damage, failing to prevent further loss, and accepting the first settlement offer without reviewing it. Staying organized, documenting everything thoroughly, and understanding your policy terms can make a significant difference in how your claim is handled.
Nobody buys insurance thinking they’ll actually need to use it. Then a pipe bursts, a car gets rear-ended, or a storm tears half the shingles off the roof, and suddenly you’re on the phone with an adjuster hoping the whole thing goes smoothly.
Sometimes it does. Often, though, it doesn’t — and it’s rarely because the insurer was out to get you. In our experience reviewing how claims actually play out, most delays and denials trace back to something the policyholder did (or didn’t do) early on: waited a few days too long to report it, tossed the ruined carpet before anyone photographed it, or said something offhand to the adjuster that came back to bite them.
The good news is that almost all of this is avoidable once you know what to watch for. That’s what this guide is for — the mistakes people make, why they matter more than you’d think, and what to do instead. We’ll also get into how to decide whether filing is even worth it, and when it’s time to bring in outside help.
Should You Even File a Claim?
This is the question people skip, and it costs them. Filing isn’t automatically the right move just because something got damaged. If the repair costs less than your deductible, you’re paying for it either way — so why put a claim on your record for nothing? On the other hand, if your house just burned down, there’s no debate to have.
| Situation | File a Claim? | Why |
| Damage below your deductible | Usually not | You’ll cover it yourself anyway, and it still shows up in your claims history |
| Major fire | Yes | Rebuilding costs are almost never something you can absorb out of pocket |
| Storm damage | Usually yes | Typically covered as long as your policy terms and deductible are met |
| A small scratch or minor cosmetic issue | Depends | Weigh the deductible and repair cost against what it might do to your next renewal |
| Theft, with a police report on file | Yes | You’ve got documentation, and the losses are often substantial |
So, can a claim be denied just for missing paperwork? Yes — if the insurer can’t verify what happened because key documents are missing, that alone can hold up or sink an otherwise legitimate claim. Photos, receipts, and estimates aren’t optional extras; they’re what makes your case.
Why Claims Actually Get Delayed or Denied
Strip away the jargon and it usually comes down to a short list:
- The loss was reported too late
- Paperwork was missing or incomplete
- The damage falls under something the policy excludes
- The policy had lapsed when the loss happened
- Premiums weren’t paid
- The story changed somewhere along the way
- The insurer suspected fraud
- There simply wasn’t enough evidence to back the claim up
| Reason | Causes Delay | Can Cause Denial | Preventable? |
| Late reporting | Yes | Yes | Yes |
| Missing documents | Yes | Sometimes | Yes |
| Coverage exclusion | No | Yes | Partially |
| Policy lapse | No | Yes | Yes |
| Inconsistent statements | Yes | Yes | Yes |
| Fraud suspicion | Yes | Yes | Yes |
Look at that list again — almost every one of those is something the policyholder had some control over. That’s frustrating to hear, but it’s also good news, because it means you’re not just at the mercy of your insurer’s mood.
How a Claim Actually Moves Through the System
It helps to know the shape of the process before you’re in the middle of it. For homeowners dealing with property damage, this guide on how to file a hazard insurance claim explains the basic steps involved in submitting a claim.
- The loss happens
- You take reasonable steps to stop it from getting worse
- You report it to your insurer
- You gather evidence — photos, receipts, whatever you’ve got
- An adjuster comes out to look at the damage
- The insurer assesses what’s covered and what it’s worth
- They make a settlement offer
- You get paid, or repairs move forward
Here’s what that looks like in practice: Sarah’s basement flooded overnight after a pipe burst while she was asleep. Before she touched anything, she grabbed her phone and photographed the standing water and everything it had ruined, then rented drying equipment and kept every receipt. She called her insurer that same day instead of waiting to “deal with it later.” Because she had everything documented before cleanup even started, her adjuster had almost nothing to question — the claim moved through with barely any back-and-forth.
That’s the difference documentation makes. It’s not glamorous, but it’s the single biggest lever you control.
15 Mistakes That Trip People Up
1. Sitting on the claim too long before reporting it
Every policy has a window for reporting a loss, and waiting past it gives the insurer an easy reason to question whether the claim is even legitimate. Even if you don’t have every detail yet, call it in as soon as it’s safe to.
2. Never actually reading the policy
Most people open their policy document for the first time after something’s already gone wrong, which is exactly the wrong time to discover an exclusion. The NAIC’s insurance coverage guidance explains why understanding policy terms, exclusions, deductibles, and claim notification requirements matters.
3. Skipping proper documentation of the damage
This one alone probably decides more claims than anything else on this list. Photos and videos from several angles, receipts, an inventory of what was lost — none of it takes long, and all of it matters later.
4. Throwing damaged stuff away before anyone’s seen it
It’s tempting to just clean up and move on. But once the ruined carpet is at the curb, so is your evidence. Wait for the adjuster’s sign-off, or at minimum photograph everything before it goes in the trash.
5. Telling the story a little differently each time
Say something slightly different to your insurer than you said to the police or your contractor, and you’ve just handed the adjuster a reason to dig deeper. Keep it factual, and keep a note of exactly what you told whom.
6. Guessing at repair costs instead of getting a real estimate
A ballpark number in your head isn’t the same as a written estimate from a licensed contractor, and insurers know the difference. Get the real number before you argue about the payout.
7. Signing off on the first offer without checking it
The first number an insurer offers isn’t necessarily their best or final one. Hold it up against your documented damages and repair quotes before you agree to anything.
8. Letting the damage get worse
If a storm rips a hole in your roof and you don’t cover it, and it keeps leaking for another two weeks, don’t be surprised if the insurer pushes back on part of the payout. Most policies expect you to take reasonable steps to stop things from getting worse.
9. Missing a deadline you didn’t know existed
Reporting windows, proof-of-loss deadlines, appeal timelines — they’re all different depending on your state and your insurer, and missing any of them can put your whole claim at risk. Write the dates down the moment you file.
10. Hiring an unlicensed contractor for repairs
It might save you money upfront, but unlicensed work can complicate your claim, create liability headaches, and sometimes void coverage on the repair itself. Check the license before you sign anything.
11. Posting about it on social media
This one catches people off guard. Insurers do look at public posts during investigations, and something as innocent as a vacation photo posted while you claimed to be out of work can create problems that have nothing to do with whether your claim is legitimate. Easiest fix: just don’t post about an open claim at all.
12. Padding the numbers
Even a small exaggeration can trigger a fraud investigation, stall the parts of your claim that were completely legitimate, and in the worst cases lead to actual charges. Report what happened. Nothing more.
13. Going quiet when the insurer asks for something
Ignoring a request for documents or a statement is one of the fastest ways to stall your own claim. If you need more time, say so — but respond.
14. Not keeping track of who said what and when
Phone calls get forgotten. Promises made verbally are hard to prove six weeks later. A simple log — date, name, what was discussed — saves you a lot of grief.
15. Giving up after a denial
A lot of people treat a denial as the final word. It usually isn’t. Most insurers have a reconsideration or appeal process, and it’s often worth using.
Things You Probably Shouldn’t Say to an Adjuster
What comes out of your mouth matters almost as much as what’s in your file. Understanding how adjusters evaluate claims can help you prepare, so read our guide to home insurance claim adjuster secret tactics before discussing a disputed property claim. A few phrases are also worth avoiding:
- “It was probably my fault.” Let an actual investigation determine fault — don’t hand it to them in casual conversation.
- “I’m guessing it cost around…” Only put a number out there if it’s backed by a receipt or a written estimate.
- “Everything was destroyed.” Describe what you’ve actually confirmed, not what you assume happened in the heat of the moment.
If you’re not sure about something, it’s fine to just say you’re not sure. That’s a better answer than a guess that turns out to be wrong.
Mistakes That Show Up by Insurance Type
Home insurance: Not stopping further damage after the initial loss, and having no home inventory to point to when it matters.
Auto insurance: Skipping the police report, not photographing the scene, and casually admitting fault before anyone’s actually determined who was at fault.
Health insurance: Going out-of-network without checking first, or skipping a pre-authorization that turns out to be required.
Life insurance: Beneficiary paperwork that’s outdated or filled out incorrectly, and missing supporting documents that hold up the whole payout.
Renters insurance: No proof you actually owned the things that were stolen or damaged, which makes the whole claim much harder to value.
What’s Usually Covered and What Usually Isn’t
A lot of coverage confusion comes down to assuming something’s included when it’s actually excluded, or only partially covered.
| Often Covered | Often Excluded or Limited* |
| Fire | Flood (unless you’ve added separate coverage) |
| Wind | Earthquake (unless endorsed) |
| Theft | Normal wear and tear |
| Vandalism | Damage from neglected maintenance |
*This varies by policy — check your own declarations page and exclusions section rather than assuming.
What to Have Ready: Documentation Checklist
- Policy number
- Photos and videos of the damage
- Police report, if there is one
- Receipts for anything damaged or lost
- A written repair estimate from a licensed contractor
- Medical reports, if injury is involved
- Witness statements
- A log of every conversation with your insurer
- Your claim number, once you have it
Getting Ready Before Anything Even Happens
The best time to prepare for a claim is long before you need one:
- Photograph every room in your home once a year, minimum
- Save receipts for big purchases somewhere digital, not just in a drawer
- Keep your policy documents backed up in the cloud
- Have your insurer’s claims line saved somewhere you’ll actually find it
- Know what your deductible actually is for each type of coverage
- Look over your coverage limits every year, especially after a renovation or a big purchase
Roughly How Long It All Takes
| Stage | Typical Time |
| Reporting the claim | Right away |
| Inspection | About 2–14 days |
| Investigation | Varies a lot |
| Settlement offer | Depends on insurer and state |
| Payment | Per your policy terms and applicable state rules |
Take these as rough guides, not promises — the real timeline depends on your insurer, how complicated the claim is, and where you live.
Your State Actually Matters Here
Insurance is regulated state by state in the U.S., which means your rights during a claim look different depending on your zip code. A few things that shift from state to state:
- How long you have to report a loss or file proof of loss
- What your appeal rights actually look like
- What counts as unfair or bad-faith claims handling
- Whether insurers face strict deadlines to respond or settle
Don’t assume your claim will unfold exactly like a friend’s did in another state. When in doubt, your state insurance department’s website is the most reliable place to check.
How AI Is Actually Changing Claims Right Now
By 2026, most insurers are using some form of AI throughout the claims process, and it’s worth understanding how that affects you as a policyholder:
- Photo analysis – AI tools can gauge damage severity from your submitted photos, which is part of why clear, well-lit images matter more than they used to.
- Document verification – Receipts, estimates, and reports may get checked automatically for authenticity and whether they line up with each other.
- Fraud detection – Automated systems flag anything that looks off, like a timeline that doesn’t add up or a string of recent claims.
- Automated estimates – Some insurers generate an initial repair estimate through AI. You can still push back on it with your own contractor’s number.
- Metadata consistency – Timestamps and file details on your photos and documents can get compared against the story you’ve told.
None of this means the system is out to trip up honest claimants. It just means clean, consistent, well-documented claims tend to sail through faster than the ones with gaps or contradictions.
What Can Trigger a Closer Look
- Several recent claims from the same policyholder
- Statements that don’t quite match across different reports
- Missing receipts or documentation
- Photos that look edited or altered
- A timeline that doesn’t add up
- Repair estimates that seem inflated
- Big policy changes made right before a loss
None of this automatically means fraud. Plenty of honest claims get extra scrutiny simply because something in the paperwork was thin or inconsistent — which is exactly why the documentation habits above are worth the effort.
If Your Claim Gets Denied, Here’s What Actually Helps
- Read the denial letter closely and figure out the actual stated reason
- Check that reason against your real policy language, not what you assumed it said
- Pull together any evidence that directly addresses that reason
- Ask for reconsideration through your insurer’s internal process
- File a formal appeal if that doesn’t resolve it
- Reach out to your state insurance department if something feels off
- Talk to an attorney if the dispute is complicated or you suspect bad faith
When It’s Worth Bringing In Help
You don’t need a professional for every claim, but there are moments where it pays off:
- Public adjusters advocate for you and help document and value a loss — most useful on large or complicated property claims where the damage assessment itself is being contested.
- Attorneys are worth a conversation when there’s a coverage dispute, a suspected bad-faith denial, or serious money on the line. If you’re dealing with a disputed auto claim, our guide explains when you may need an auto insurance claim attorney.
- Independent appraisers offer a neutral valuation when your number and the insurer’s number are far apart — many policies actually include an appraisal clause for exactly this situation.
- Your state insurance department can look into complaints and clarify your rights, usually at no cost to you.
Habits That Actually Improve Your Odds
- Read your policy before you ever need it, not after
- Back up key documents somewhere in the cloud
- Keep a home inventory updated year to year
- Photograph valuables now and then, and jot down serial numbers
- Hold onto maintenance records for your home and car
- Respond to insurer requests quickly, even briefly
- Go through the settlement math line by line before you accept it
Key Takeaways
- Most denials are avoidable with a bit more preparation
- Documentation is your best evidence, hands down
- Read the policy before you’re forced to
- Report losses right away, and keep the story straight
- Don’t exaggerate, don’t speculate out loud
- Write down every conversation with your insurer
- A denial isn’t necessarily the end of the road
Wrapping Up
Getting a claim paid fairly usually isn’t about luck — it’s about the groundwork you laid before and during the process. The people who come out of a claim feeling like the system actually worked are almost always the ones who documented everything, understood their policy ahead of time, and communicated clearly instead of guessing.
Set aside an afternoon to review your policy, snap some photos around the house, and back up your important documents somewhere safe. It’s a small effort now that saves a lot of frustration later — and when you’re unsure about anything specific to your situation, your insurer and your state insurance department are the two best places to ask.
Frequently Asked Questions
What’s the biggest mistake people make when filing a claim?
Poor documentation, by a wide margin. Insurers lean heavily on photos, receipts, and records to verify a claim, and gaps in that evidence are one of the most common reasons things get delayed or denied.
Can an insurer deny a claim just because I reported it late?
Yes. Most policies spell out a reporting window, and missing it gives the insurer grounds to deny the claim.
Should I just take the first settlement offer?
Not without checking it first. Compare it against your documented damages and repair estimates, and push back if the numbers don’t add up.
What should I actually keep on file for a claim?
Your policy number, photos and videos, receipts, a written repair estimate, a log of communications, and your claim number once it’s assigned.
Does social media actually affect a claim?
It can. Insurers sometimes review public posts during an investigation, and something that looks inconsistent with your reported damage can complicate things — better to just stay off social media about it while the claim’s open.
How long does a claim usually take?
It really depends on your insurer, your state, and how complicated the claim is, but inspections typically happen within two to fourteen days of filing.
What if I gave the wrong information by accident?
Call your insurer as soon as you catch the mistake and correct it in writing. An honest error handled openly is treated very differently than something that looks deliberate.
Can a closed claim be reopened?
Often, yes — especially if new damage turns up or new information comes to light. It depends on your insurer and policy.
Is hiring a public adjuster worth it?
For a large or complicated property loss, often yes. For something small and straightforward, probably not necessary.
What actually counts as insurance bad faith?
It refers to an insurer handling a claim unreasonably — an unjustified denial, or delays with no real cause. It’s a legal concept, and it usually needs a professional to evaluate properly.
Can I appeal a denial?
Yes, almost always. Most insurers have a formal appeal or reconsideration process, and you can also escalate to your state insurance department if you’re still stuck.
Does filing a claim always bump up my premium?
No. It depends on the type of claim, your history, and how your specific insurer prices risk.
Can I file more than one claim in a year?
There’s usually no hard cap, but several claims in a short window can affect your next renewal and may draw a closer look during review.
What if I never kept receipts?
Bank statements, credit card records, product manuals, photos of the item in use, even old order confirmations can sometimes stand in as proof of ownership and value. To know more about credit score, read this article as well.
Do insurers actually record claim calls?
Many do, often with a heads-up at the start of the call. Treat anything you say on the phone as part of your official claim record.
Should I get my own contractor out before the adjuster shows up?
Usually better to wait until after the inspection — though there’s nothing wrong with getting a preliminary written estimate to have on hand for comparison.
Can I switch insurance companies while a claim is still open?
You can, but the insurer you were with when the loss happened is still on the hook for resolving that claim under the policy that was active at the time.
Does filing a claim hurt my insurance score?
Claims history can factor into how insurers price your future coverage, but exactly how much it matters varies by carrier and by state.
Disclaimer
This article is for general informational purposes only and does not constitute insurance, legal, financial, or professional advice. Insurance coverage, claim deadlines, exclusions, settlement procedures, and appeal rights vary by policy, insurer, and state. Review your policy documents and consult your insurer, state insurance department, or a qualified professional for guidance specific to your situation.